
What matters most is not only the size of the outflows, but how they occurred. Redemptions were steady and extended over several weeks rather than concentrated around a single shock. On average, ETFs were net sellers of roughly 500 to 1000 $BTC per day, a pace that points to deliberate exposure reduction rather than panic-driven exits.
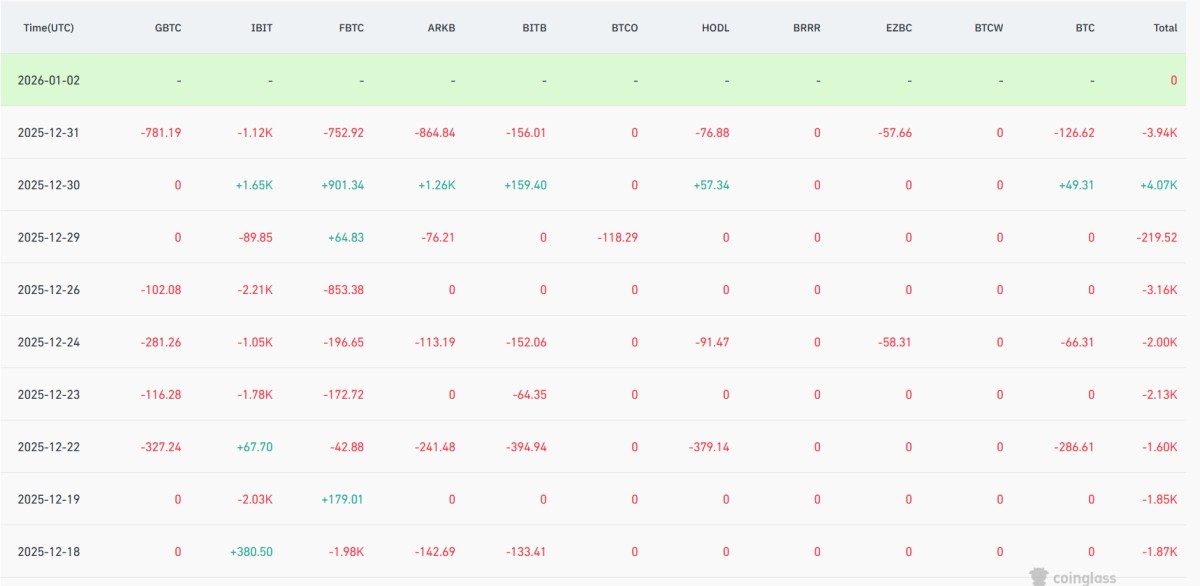
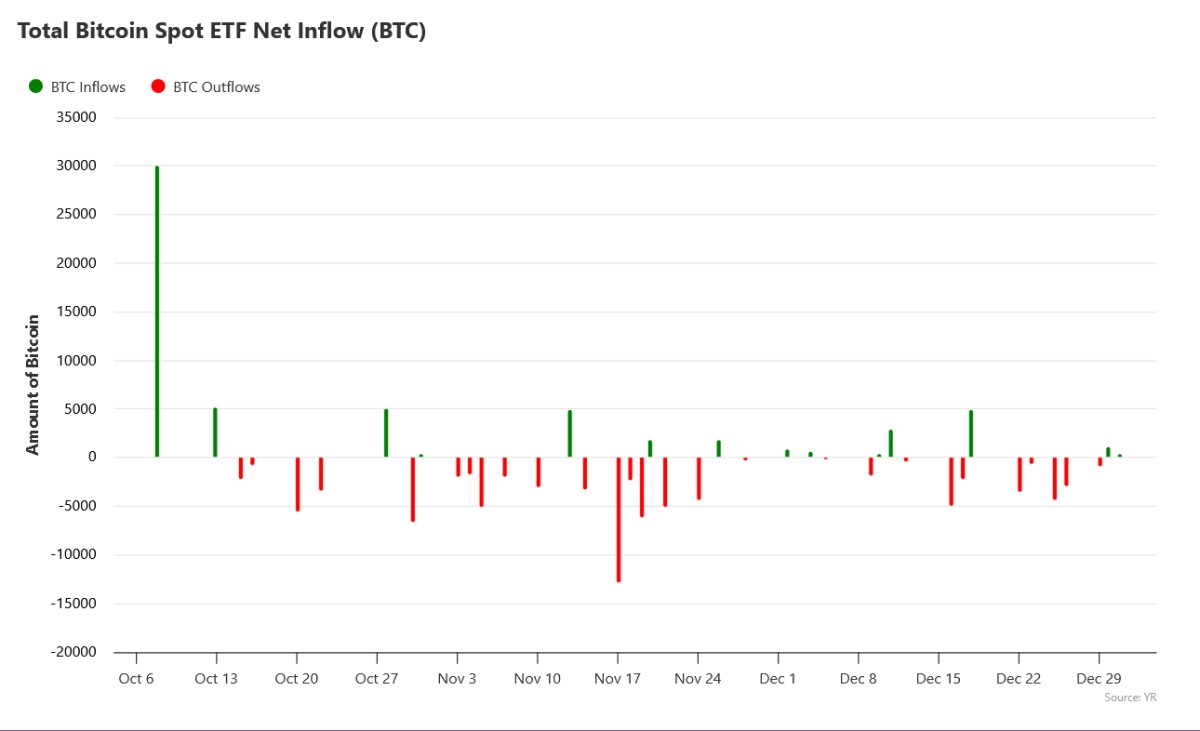
Because spot ETFs must sell underlying Bitcoin to meet redemptions, these flows translated directly into additional supply entering the market. The effect was visible in price behavior. Bitcoin did not experience a sharp breakdown. Instead, it traded within a broad range, struggled to sustain breakouts, and consistently faded after short-lived rallies. This is a typical response when continuous supply meets stable but cautious demand.
ETF activity has played a central role in shaping recent liquidity conditions. When ETFs are net buyers, pullbacks tend to find support quickly and upward momentum builds more easily. When ETFs are persistent sellers, rallies face friction. Volatility can increase, but price struggles to establish a clear direction as buying interest is absorbed by ongoing distribution.
This environment should not be interpreted as a breakdown in Bitcoin’s longer-term outlook. Rather, it reflects a shift in positioning. Institutional investors appear to have moved into a risk-reduction phase, adjusting exposure amid uncertain macro conditions and tighter liquidity.
The next meaningful change in price behavior is likely to depend on ETF flows themselves. A slowdown in redemptions, or a return to consistent inflows, would reduce supply pressure and improve the durability of upside moves. Until then, Bitcoin is likely to remain range-bound, with advances proving difficult to sustain.
In summary, while the market may appear stable on the surface, ETF flow data suggests underlying demand has softened. Understanding these mechanics helps explain why recent price action has lacked conviction despite periods of elevated trading activity.